In collaboration with Paddle, we surveyed over 100 European SaaS companies, ranging from early-stage ventures to late-stage growth. The report evaluates key performance metrics including growth, revenue retention, and operational efficiency, which are critical to navigating the current market environment.
The report also explores public market valuations, M&A trends and fundraising activity in the European SaaS sector. It includes a detailed review of deal activity, highlighting quarterly trends and providing country-specific analysis.
Alexis Scorer, Partner at GP Bullhound, commented: “This year’s survey demonstrates encouraging progress across the European SaaS sector, with companies displaying continued improvements in gross margins, operational efficiency, and overall profitability. Nearly half of companies surveyed are now EBITDA positive, highlighting the continued emphasis on capital efficient growth. Despite subdued fundraising volumes, an increase in larger private placements and increasing M&A activity underscores the sector’s adaptability and resilience. With Public market SaaS valuations now above the three-year average and a renewed focus on profitable growth, the industry is well-positioned to benefit from an improving Macroeconomic environment in 2025.”
GP Bullhound European SaaS survey key takeaways
Growth rates remain stable for late-stage SaaS. Despite a slight overall decrease in growth in 2023 across the cohort surveyed, growth rates for the €50m+ ARR companies are broadly in line with the previous year.
Continued improvement in operational efficiency. ARR per FTE is approaching €150k for growth-stage companies and remains significantly above 2021 levels for €50m+ ARR companies, despite a slight reduction from last year.
Stable year-on-year Net Revenue Retention of 110%. Median Net Revenue Retention was 110% – 112% in 2023 for companies surveyed, nearly identical to rates these companies exhibited in 2022.
Broad improvements in Gross Margin year-on-year. All ARR cohort groups saw improvements in gross margin ranging from 1% – 7%, reversing the trend highlighted in last year’s survey.
Nearly half of all SaaS companies surveyed are now profitable. Continued improvements in profitability, with 44% of all companies now EBITDA positive, compared with ~33% in last year’s report.
Public Market European SaaS
SaaS valuations have increased above the 3-year mean. Average European SaaS valuations are trading at 6.7x, above the 3-year average of 5.4x.
Growing emphasis on profitable growth. Correlation between public market valuations for the European SaaS index and Rule of 40 performance has increased significantly, with a renewed emphasis on growth versus last year.
US vs EU SaaS valuation gap diverging again. Following a recent period of convergence between public US and European SaaS valuations, listed US SaaS companies are now valued at a 20%-40% premium over their European counterparts.
European SaaS Deal Activity
Resilient M&A volume in 2024 YTD. Strong M&A activity in the YTD period signals early stages of recovery following several quarters of consecutive growth.
Growing proportion of larger late-stage fundraisings. Whilst fundraising activity remains muted, deal value has begun to recover with a notable increase in the proportion of $250m+ transactions in 2024 YTD.
Enquiries For any enquiries, please contact: Alexis Scorer, Partner, at alexis.scorer@gpbullhound.com For press inquiries, contact: press@gpbullhound.com.
About GP Bullhound GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 13 offices spanning Europe, US and Asia. For more information, please visit www.gpbullhound.com.
Mentimeter is a SaaS platform dedicated to transforming group learning and communication into inclusive and engaging experiences. Used by 99% of leading universities and 95% of Fortune 500 companies, Mentimeter simplifies the process of gathering live feedback and encouraging active participation to help educators and business professionals achieve better outcomes and increased productivity in meetings, training sessions, and classrooms.
Founded in 2012 and headquartered in Stockholm, Mentimeter is used by 99% of leading universities and 95% of Fortune 500 companies. It simplifies the process of gathering live feedback and encouraging active participation, helping educators and business professionals achieve better outcomes and increased productivity in meetings, training sessions, and classrooms.
This secondary transaction of €63 million, involved Bure Equity AB (publ) investing €46 million and GP Bullhound contributing €17 million. The primary sellers in the transaction were the investment firm Alfvén & Didrikson. As a result of this transaction, Bure Equity AB (publ) and GP Bullhound Fund VI have become new shareholders in Mentimeter, ranking as the company’s third and sixth largest shareholders, respectively.
The company does not gain any proceeds from this transaction and intends to continue its fast and profitable growth. Its growth strategy includes:
Continued investment in the platform and product development to outgrow the competition and claim market leadership in new attractive segments and market verticals.
Accelerating investments in enterprise sales and partnerships.
Investing in product and brand awareness in key markets.
GP Bullhound’s Partner Joakim Dal commented, “Mentimeter’s innovative approach to solving the gigantic and costly problem of lack of engagement for customers everywhere has truly set them apart. GP Bullhound is proud to partner with a company that continually redefines its market, and we are committed to supporting their ambitious growth trajectory.”
Mentimeter’s CEO Johnny Warström added, “I am very pleased to welcome Bure and GP Bullhound as shareholders in Mentimeter. Alfvén & Didrikson has been an active and supportive shareholder for a long time, and I look forward to a good and long-term collaboration with Bure and GP Bullhound.”
GP Bullhound invested through Fund VI, which also includes late-stage ventures such as LeoLabs, EcoVadis, CoverManager, and Sesame. By strategically investing in the AI-led software revolution, GP Bullhound focuses on the sustained growth of software by backing category leaders in the later stages of venture. The investment was made with the support of the LFF 2 initiative, a cooperation between the Société Nationale de Crédit et d’Investissement (SNCI) and the European Investment Fund (EIF), aimed at supporting the diversification of the Luxembourg economy by enhancing financing provisions to innovative companies.
We guide SaaS founders, CEOs and investors on how to navigate market challenges while highlighting the performance indicators of companies most likely to emerge stronger.
We surveyed over 100 SaaS companies across Europe in partnership with HSBC Innovation Banking, from startups to late-stage scaleups. We analyse the trends and compare key metrics including growth, headcount productivity and revenue retention, which are critical to navigating the current environment.
The report also explores public market valuations, M&A and fundraising in European SaaS, including the quarterly evolution of deal activity along with a country-specific breakdown of what’s trending.
Alexis Scorer, Partner at GP Bullhound, commented: “The focus on capital efficient growth highlighted in last year’s report has been evidenced by this year’s survey, indicating broad improvements in operational efficiency across the European SaaS sector. Despite the continued decline in SaaS fundraising volumes, M&A activity has proved resilient and remains well above pre-pandemic levels for European SaaS.”
European SaaS survey – key takeaways
Median ARR growth for SaaS companies with over €25m ARR declined from 44% in 2021 to 27% in 2022
Significant increase in ARR per FTE to €124k; average grows by 30% vs last year’s report
Slight improvement in Net Revenue Retention from 104% to 105% YoY
Median gross margins fell from 80% in last year’s report to 75% this year
Over a third of companies surveyed now profitable and c.40% of cohorts with ARR growth below 60% are profitable
European SaaS deal activity– key takeaways
Despite the decline in fundraising volume since the Q2 2022 peak, total funds raised are above pre-Covid levels $4bn–$5bn per quarter
SaaS M&A activity remains resilient with 178 transactions per quarter 2023 YTD, 30% above 3-year average
European SaaS public market – key takeaways
Valuation gap between public US and European SaaS companies stabilised in 2023
Revenue multiples for listed European SaaS companies recovering from c.4.3x at the start of the year to 4.8x in October
About GP Bullhound GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.
Apps have become the interface to our modern world. We already spend half of our waking hours using them, and their influence is only set to increase.
Apps are everywhere and run on everything. To cater to the evolving needs of users, be platform agnostic, and control the customer experience, companies have had to focus on developing desktop and mobile applications. This has not only multiplied costs and complexity, but also decreased development speed.
However, after years of improvements, there is now an app platform that has become better than all others, and may soon very well be the only one that is relevant. This platform is the web. The web not only delivers the same user experience as other platforms but also offers a set of fundamental advantages.
The web is the only platform where apps never need to be downloaded, the only platform where its apps run on all devices and operating systems, the only platform that is used by everyone, and the only platform that is not controlled by large tech corporations. These factors make the web the only viable contender for harmonising the fragmented world of app platforms – and this shift has already begun.
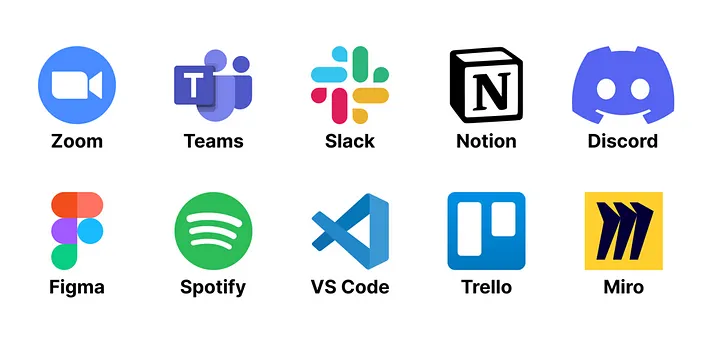
As users, we almost exclusively use apps built for the web already. Products we love and rely on daily like Zoom, Slack, Notion, and Figma are nothing but web apps put in a shell to appear like a desktop app that we are more used to.
Not only can we feel this shift, quantitatively it is also clear that:
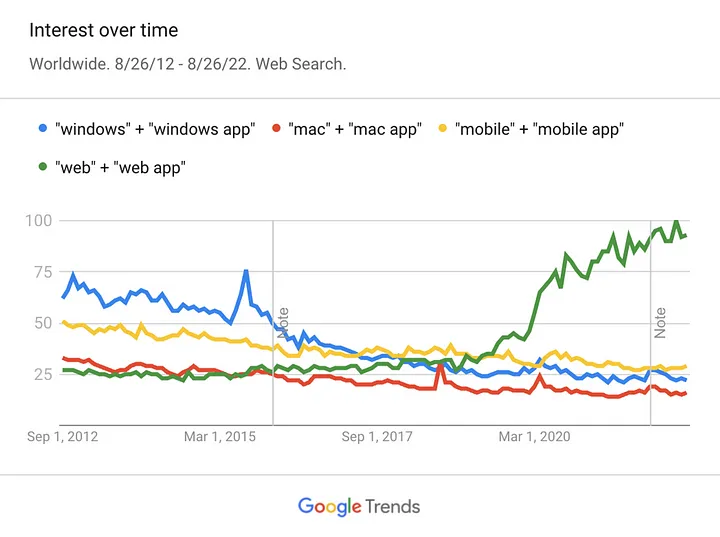
Web app usage is increasing faster than the usage of other apps – growing more than 50% in 2020-2021, and now getting more than 2x the search interest of Windows and Mac apps combined
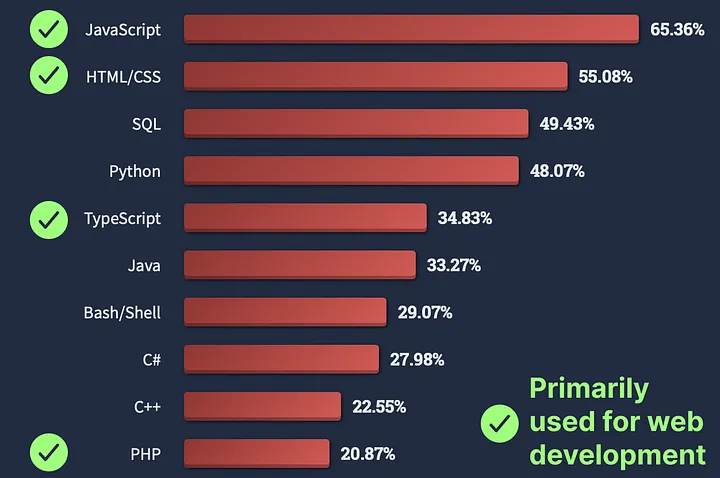
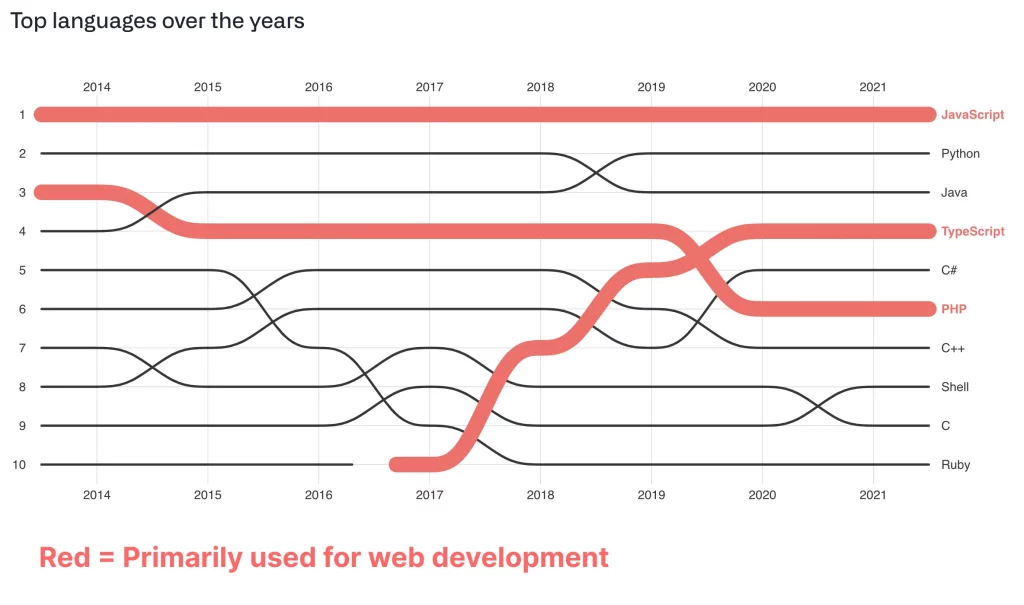
Web-related programming languages have taken over – being the most popular languages with a wide margin, making up three out of the top five, including the #1 spot
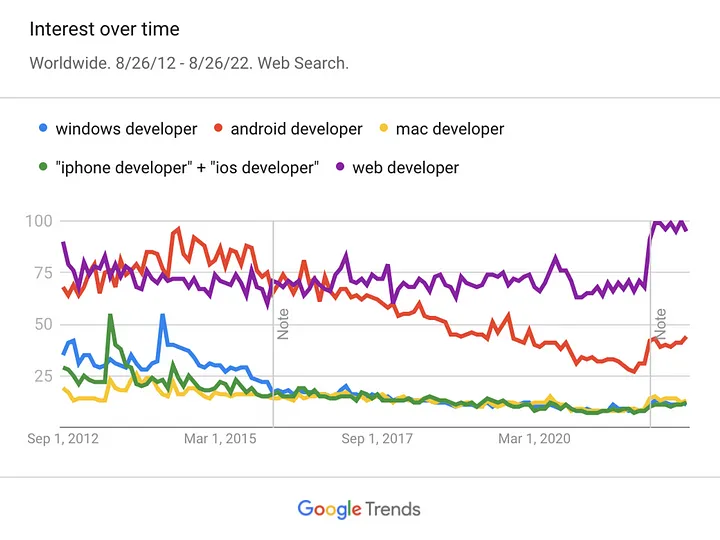
Companies are screaming for web developers – with interest for the category now being higher than for Windows, Mac, iPhone, and Android developers combined
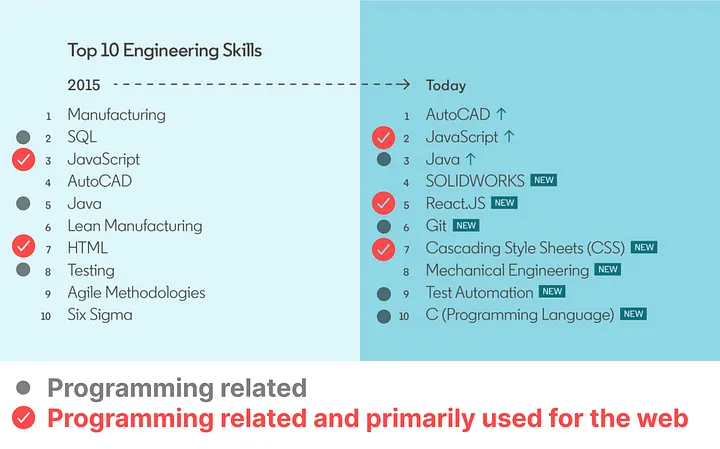
Engineers are rushing to web development – with skills related to it making up three out of the top five programming skills on LinkedIn, up from two in 2015, and now taking #1
Why? As apps have become the interface to our modern world, the value in harmonising the fragmented world of app platforms has never been higher
Half of our waking hours are spent using apps on our phones and computers. From working, to socialising and shopping, the majority is done using apps. They are the interface to our modern world, and are only going to play a bigger part as the world gets increasingly digital.
Apps today run on many different devices and platforms – including phones, computers, and on the web. This multitude of app platforms adds much work and complexity for companies and developers, as well as for users:
Companies and developers need to develop separate apps for each platform, which means multiplying the required work and complexity compared to only developing the app once. There are at least nine different versions of Microsoft Office, for example, and over 25 versions of Netflix
Users today need to download their apps once for each platform they use (with varying availability) and they need to make sure their files and settings are synced
Harmonising this fragmented world of app platforms would therefore bring immense value for companies, developers, and users:
For companies and developers, a single platform would make app development faster, less complex, and less expensive as they would only need to develop the app for one platform
For users, a single platform would mean a single download and installation, as well as no continuous work keeping files and settings synced across platforms
How? The web has fundamental advantages over all other platforms which makes it the best and only viable option for modern apps
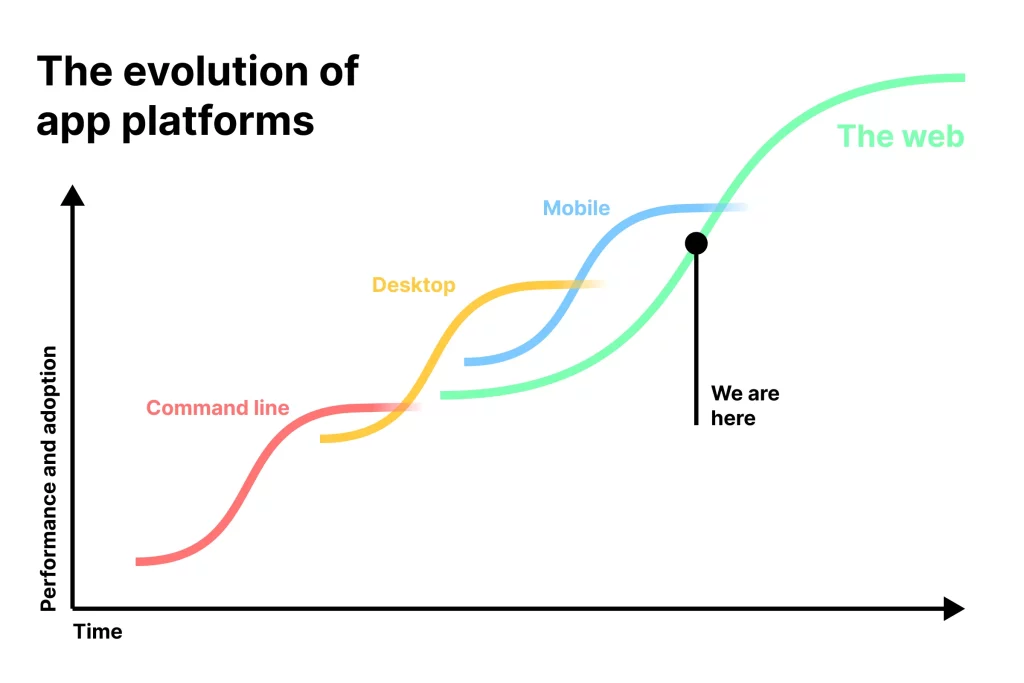
APPS EVOLVED FROM THE COMMAND LINE TO THE DESKTOP, AND TO MOBILE DEVICES. THE WEB STARTED IMPROVING ALREADY BEFORE THE LAUNCH OF MOBILE, BUT AT A SLOWER PACE
Historically, native platforms such as Windows and Mac were the only way to go if you wanted your app to do anything “advanced” like work offline, send notifications, render 3D graphics, or access the device’s storage, camera, or Bluetooth. This is no longer the case. The web has seen drastic improvements over the last decades and can now do everything that only native platforms could do before.
On top of that, the web has a set of fundamental advantages over platforms, making it the best and only viable option for creating modern apps:
Web apps never need to be downloaded: They open instantly and can be shared with a simple link (URL)
Web apps run on all devices and operating systems: Users can start working on their phone and then opben the same URL on their computer, while their progress, files, and settings are synced automatically
The web is used by everyone: Browsers are installed on all computers and phones, and developers only need to write one codebase for one app to reach users
The web is not controlled by big tech: Apple controls which apps get to be distributed and run on their iPhone and iPad platforms. This enables them to decide which apps are allowed to see the light of day, while also taking 30% of all revenue that is generated from those that do
What? The shift has already begun and the web is establishing itself as the primary app platform of the future
The data corroborates the web’s ascendance as the primary app platform of the future. Let’s break it down first for users, then for companies and developers.
Users already use web apps almost exclusively as most apps installed are nothing but web apps put in a shell to appear and run like desktop apps.
ALL OF THESE APPS, EVEN WHEN ON YOUR DESKTOP, ARE BUILT ON WEB TECHNOLOGIES
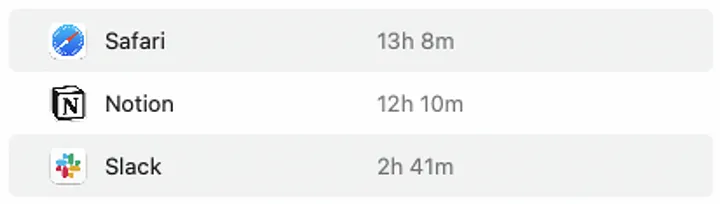
Users likely use the web browser more than any other app on their computer, and the others used are most likely web apps as well.
TOP 3 APPS USED ON THE AUTHOR’S COMPUTER – THE WEB BROWSER SAFARI BEING THE MOST USED WHILE #2 AND #3, NOTION AND SLACK, ARE BOTH WEB APPS PUT IN A DESKTOP SHELL
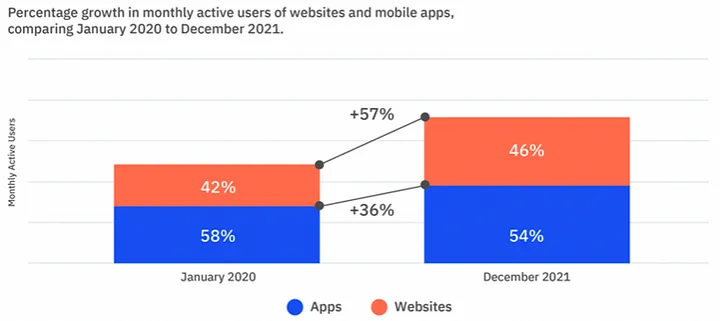
Usage of websites and web apps is increasing much faster than usage for regular apps +57% for web apps, +36% for regular apps 2020-2021
SOURCE: AMPLITUDE LAB – 2022 APPS VS WEBSITE TREND REPORT
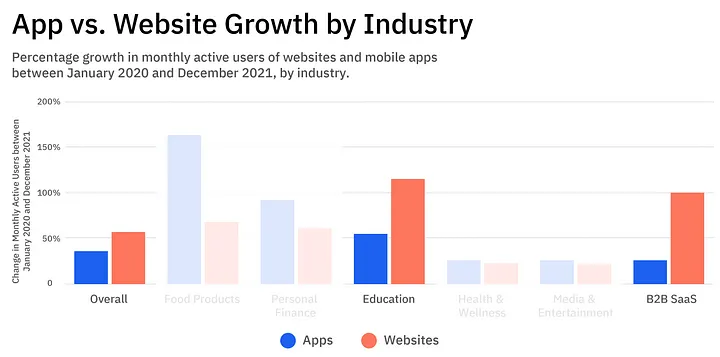
The shift towards web apps is especially evident looking at B2B SaaS and education products which are more often used on the computer, while consumer-oriented apps – more commonly used on the phone – are still used more as regular mobile apps
SOURCE: AMPLITUDE LAB – 2022 APPS VS WEBSITE TREND REPORT
The popularity of web apps can also be seen increasing in Google search
SOURCE: GOOGLE TRENDS
Web developers are now the most sought after with search interest for them higher than for Windows, Mac, iPhone, and Android combined
SOURCE: GOOGLE TRENDS
Web development skills are the most popular programming skills on LinkedIn –making up three out of the top five, up from two in 2015 and now taking the #1 spot
SOURCE: LINKEDIN
The web language JavaScript is the world’s most popular programming language and is giving the web an unfair advantage with its unmatched developer community
SOURCE: STACK OVERFLOW
This advantage is further fueled by other web-related languages becoming increasingly popular as well – most notably TypeScript
SOURCE: GITHUB
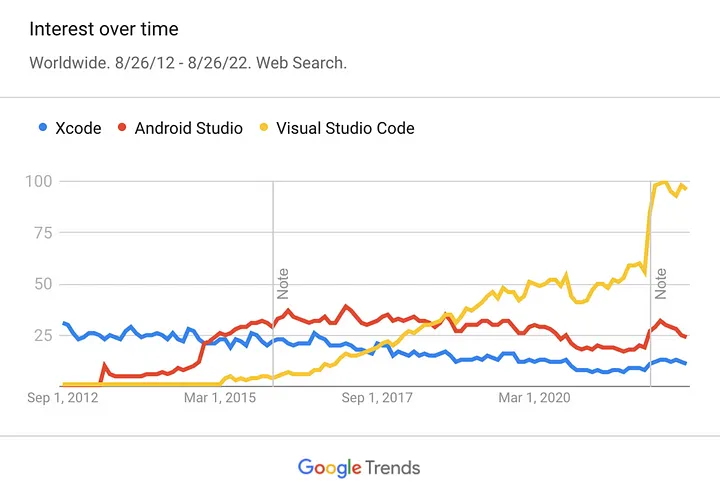
Tools for “native” app development are becoming less popular in favour of tools for web development. Xcode is the primary software used for developing iPhone and Mac apps, Android Studio for Android apps, and Visual Studio Code for web apps
NOTE: THE SHARP INCREASE IN EARLY 2022 IS EXPLAINED BY GOOGLE MAKING IMPROVEMENTS TO THEIR DATA COLLECTION SYSTEM – MEANING THE POPULARITY OF VISUAL STUDIO CODE WAS LIKELY CALCULATED TOO LOW BEFORE SOURCE: GOOGLE TRENDS
What this means for us
For us at GP Bullhound, having identified the web’s increasing dominance of app platforms means that:
We know of a strong tailwind not obvious to the average investor – putting us at an advantage
We can identify the winners in the web landscape early and with conviction – as developer preference is often a leading indicator of future success in this space. Notable exits of companies that were well-known by web developers to be the category leaders years ahead include: MongoDB with a current market cap of $15bn after going public in 2017, GitHub which was acquired for $7.5bn by Microsoft in 2018, and Figma which was acquired by Adobe for $20bn in 2022
We can isolate other categories which are prone to disruption from web-based alternatives – creative apps being an example. Similar to how Figma disrupted the interface design space by making it inherently web-based and collaborative, the same is likely to happen with video editing, like Runway or Descript, or coding, like Replit, and other creative domains
The investment landscape
Building on this, we have identified four categories of companies that are enabling the web’s ascendance and will benefit greatly from this shift. These are:
Web building blocks – the infrastructure and components that developers use for building, launching, and running web apps. Examples include APIs, cloud and backend platforms, databases, frameworks, and other technologies, such as Vercel and Supabase
Web design and developer tools – the tools used for designing, coding, and testing web apps. Examples include the interface design software, IDEs in which developers write code, and other apps used throughout the web development process, like Replit and Framer
Web browsers – the apps and interfaces used for accessing and interacting with the web and web applications. While there have been a few dominant names like Chrome and Safari, new ones that try to reinvent the experience are popping up, like Arc by The Browser Company and DuckDuckGo
Web apps could themselves be classified as a fourth category, but seeing that almost all modern apps are web apps, this category would include the entire world of modern software, such as Notion and Discord
Looking at web development from a value chain perspective, like splitting it up into stages of planning, designing, coding, and shipping, it quickly becomes evident which companies are set to win in this space. As we continue to monitor this landscape and its most recent developments, stay tuned for further insights on this topic. Subscribe below to receive the latest research and sector updates from GP Bullhound.
About GP Bullhound GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 13 offices spanning Europe, the US and Asia. For more information, please visit www.gpbullhound.com.
*No information set out or referred to in this communication shall form the basis of any contract. The issue of this GP Bullhound blog posting (the “report”) shall not be deemed to be any form of binding offer or commitment on the part of GP Bullhound or any of its affiliates or subsidiaries. This report is provided for use by the intended recipient for information purposes only. It is prepared on the basis that the recipients are sophisticated investors (so-called “professional clients” in the meaning of Annex II of Directive 2014/65/EU on markets in financial instruments, or their equivalent elsewhere) with a high degree of financial sophistication and knowledge. This report and any of its information is not intended for use by private or retail investors in the UK or any other jurisdiction where access, use or availability of this information would be unlawful. This report does not provide personalized advice or recommendations of any kind. You, as the recipient of this report, acknowledge and agree that no person has nor is held out as having any authority to give any statement, warranty, representation, or undertaking on behalf of GP Bullhound in connection with the contents of this communication. Although the information contained in this report has been prepared in good faith, no representation or warranty, express or implied, is or will be made and no responsibility or liability is or will be accepted by GP Bullhound. In particular, but without prejudice to the generality of the foregoing, no representation or warranty is given as to the accuracy, completeness or reasonableness of any projections, targets, estimates or forecasts contained in this report or in such other written or oral information that may be provided by GP Bullhound. The information in this report may be subject to change at any time without notice. GP Bullhound is under no obligation to provide you with any such updated information. All liability is expressly excluded to the fullest extent permitted by law. Without prejudice to the generality of the foregoing, no party shall have any claim for innocent or negligent misrepresentation based upon any statement in this report or any representation made in relation thereto. Liability (if it would otherwise but for this paragraph have arisen) for death or personal injury caused by the negligence (as defined in Section 65 of the Consumer Rights Act 2015) of GP Bullhound, or any of its respective affiliates, agents or employees, is not hereby excluded nor is damage caused by their fraud or fraudulent misrepresentation. This report should not be construed in any circumstances as an offer to sell or solicitation of any offer to buy any security or other financial instrument, nor shall they, or the fact of the distribution, form the basis of, or be relied upon in connection with, any contract relating to such action. The information contained in this report has no regard for the specific investment objectives, financial situation or needs of any specific entity and is not a personal recommendation to anyone. Persons reading this report should make their own investment decisions based upon their own financial objectives and financial resources and, if in any doubt, should seek advice from an investment advisor. Forward-looking information is provided for illustrative purposes only and is not intended to serve as, and must not be relied upon as a guarantee, an assurance, a prediction or a definitive statement of fact or probability. Actual events and circumstances are difficult or impossible to predict and may differ from assumptions. Any and all opinions expressed are current opinions as of the date appearing on the documents included in this report. The information contained in this report should not be relied upon as being an independent or impartial view of the subject matter, and for the purposes of the rules and guidance of the Financial Conduct Authority (“the FCA”) and of Financial Industry Regulatory Authority (“FINRA”), this report shall not be viewed as research report and is considered marketing communication. Thus, in accordance with COBS 12.2.18 of the FCA Handbook, its contents have not been prepared in accordance with legal requirements designed to promote the independence of investment research and it is not subject to any prohibition on dealing ahead of the dissemination of the report. The individuals who prepared the information contained in this report may be involved in providing other financial services to the company or companies referenced in this report or to other companies who might be said to be competitors of the company or companies referenced in this report. For US Persons: This report is distributed to US persons by GP Bullhound Inc. a broker-dealer registered with the SEC and a member of the FINRA. GP Bullhound Inc. is an affiliate of GP Bullhound Corporate Finance Ltd. All investments bear certain material risks that should be considered in consultation with an investors financial, legal and tax advisors. GP Bullhound Inc. engages in private placement and mergers and acquisitions advisory activities with clients and counterparties in the Technology and CleanTech sectors. In addition, the persons involved in the production of this report certify that no part of their compensation was, or will be, directly or indirectly related to the specific views expressed in this report. As such, no person at GP Bullhound (including its members, directors, officers and/or employees) has received, or is authorized to accept, any inducement, whether monetary or in whatsoever form, in counterparty of promise to issue favorable coverage for the companies to which this report may relate.
Founded in March 2021 in Stockholm, Sesamy provides a comprehensive model for the consumption and monetisation of digital content, and a streamlined alternative to existing subscription models, whilst simultaneously driving a more transparent exchange between consumers and creators of content across the internet. The company has partnered with every major book publisher in Sweden and Denmark, to offer its users the option to purchase eBooks, audiobooks, and podcasts as single-purchases that can be consumed on any app or device.
The investment capital will be used to provide a new tech-driven approach to monetising news and magazines, particularly through its groundbreaking technology SmartID, launched in October 2022 with Swedish publication Breakit, which enables publishers to monetise non-subscribed readers, without cannibalising their existing revenues from digital subscriptions. The software will also include built-in price optimisation that suggests a fair price to readers and publishers alike to maximise revenues through in-depth analytics, ensuring that the platform remains at the cutting edge of usability.
Måns Ulvestam, CEO and Co-founder of Sesamy, commented: “At Sesamy, our goal is a simple yet comprehensive one: to bring back open to the internet. This is why our paywall technology is transparent and flexible for both digital content creators and consumers alike; giving consumers the option to make single purchases of articles whilst ensuring subscription revenues are not cannibalised.”
Karl Rosander, Chairman and Co-founder of Sesamy, added: “Informed by data and analytics, our ability to provide a smart paywall to businesses seeking incremental revenue streams at a time of great economic uncertainty has never been more crucial; underpinning quality journalism with a sustainable model for monetisation fit for the modern age.”
Per Roman, Managing Partner and Co-founder of GP Bullhound, commented: “We are thrilled to be continuing this exciting journey with Sesamy in the pursuit of making premium digital content accessible to all. We firmly believe that Sesamy will play a vital role in democratising access to content over the coming decade, and we look forward to supporting them on this exciting journey.”
GP Bullhound invested through Fund V. Other recent investments include EcoVadis, Connex One, Typeform, HackerOne, Whoop, Patreon, DuckDuckGo, Discord, Revolut, and Klarna, among many others.
About GP Bullhound GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 12 offices spanning Europe, the US and Asia. For more information, please visit www.gpbullhound.com.
Founded in Stockholm in 2020, Polygonflow’s mission is to create next-generation tools that provide access to the best artistic workflows within 3D software or game engines. They have built a vast library of world-class plugins that work on all major 3D software, to accelerate production processes.
Polygonflow wants to do away with old workflows and make high-end 3D creation accessible to anyone with a tablet or phone. With their proprietary software GraphN, they are aiming to revolutionise plugins creation by offering user-friendly node-based interface. Their goal is to redefine the way 3D tools are made, and give artists the right ecosystem to create, share, and sell their own tools with nodes, without ever writing code.
Adnan Chaumette, CEO and Founder of Polygonflow, commented: “To create high-fidelity 3D experiences, you need to master a patchwork of clunky software that pre-date touch devices and have steep learning curves. It wasn’t until I realised how we could connect the complexity of professional 3D automation tools with the accessibility of touchscreen that I saw the solution of how 3D could be made accessible to not just a few million professionals, but to any user with a touch device.”
GP Bullhound invested through Fund V. Other recent investments include EcoVadis, Connex One, Typeform, causaLens, HackerOne, Whoop, Patreon, DuckDuckGo, Discord, Revolut, and Klarna, among many others.
About GP Bullhound GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 12 offices spanning Europe, the US and Asia. For more information, please visit www.gpbullhound.com.
Data-driven investment process is revolutionising European financial services. European tech companies are attracting top global equity investors, corporate partners, and customers. The continent is no longer dominated by one or two hubs: unicorns have emerged in 28 countries and 98 cities, and a total of $275bn was created in exits via M&A, IPOs, direct listings, and SPACs in 2021 alone, marking an exceptional and record-breaking year for entrepreneurial activity and investment flows. Market observers believe that Europe has the strongest ever startup pipeline, on a par with the US, and the future is looking bright.
At GP Bullhound, we serve the needs of the world’s best entrepreneurs with transactional advice, research insights and capital, prioritising the development of data-driven lending products and outstanding customer experience to gain competitive advantage. We believe traditional lending products no longer have the right product or market fit: standardised term sheets with warrants and poorly designed covenants constitute a major hurdle for later-stage tech companies.
By making investments into IT and fully adopting the right data infrastructure and analytic tools across the investment process, lenders can gain higher profitability and stronger security, leading to better, simpler, and more flexible growth lending products, while also improving profitability, risk management and performance for the lenders. The rise of European tech requires a new approach to lending.
About GP Bullhound GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 10 offices spanning Europe, the US and Asia. For more information, please visit www.gpbullhound.com.
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.