When the comic below was first published in 2014, it depicted an idealised vision of the web. However, this vision has become a reality a decade later. With its websites and web applications, the web platform now has virtually all the capabilities of “native” platforms like Windows or iOS. This software is universally accessible and shareable through a simple URL and browser and can run on any device and operating system from a unified code base. Coupled with its independence from the walled gardens and App Store fees, it’s no wonder the web has emerged as the de facto standard for modern application software development.
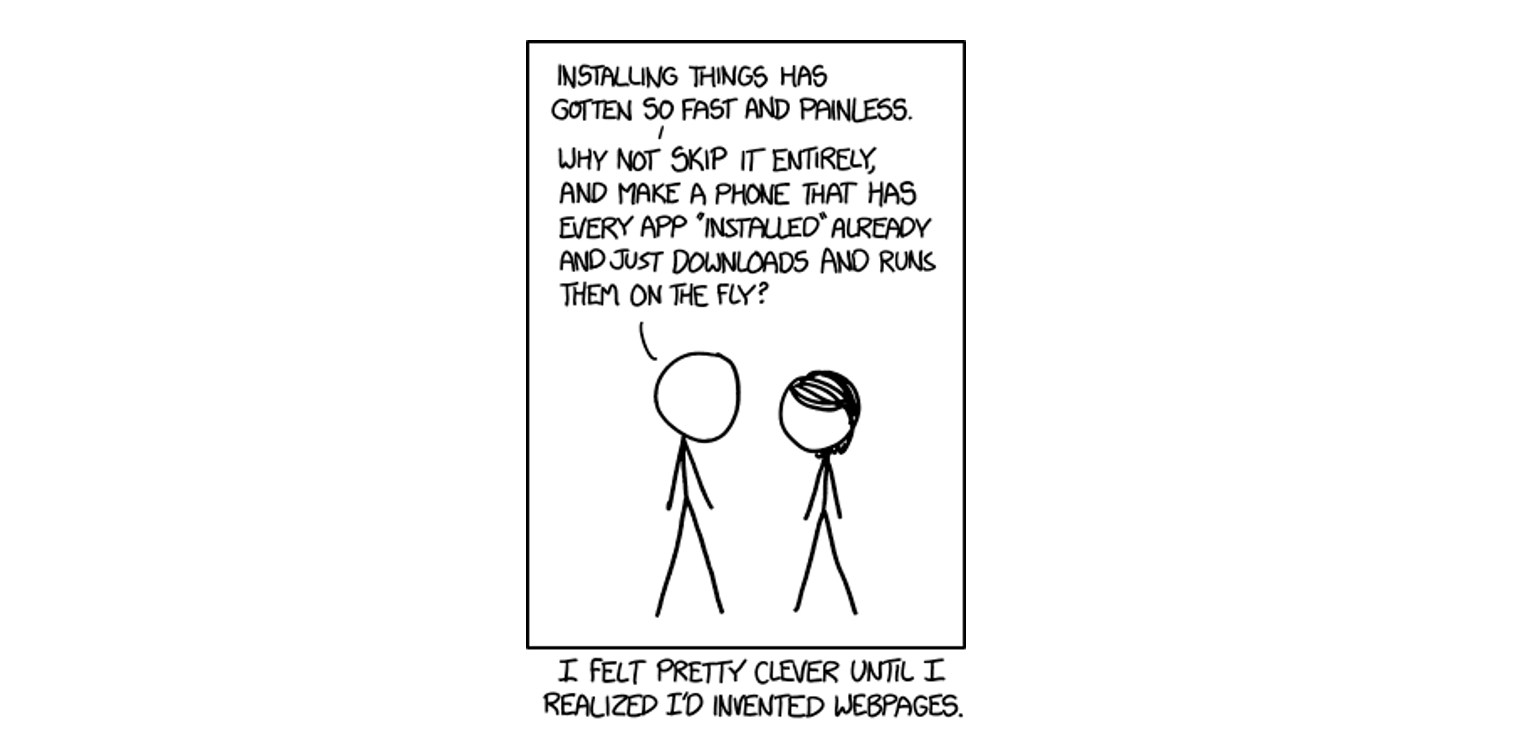
Source: xkcd

The prevalence of the web is evident as we frequently use software like Google Docs, Salesforce, and GitHub through our web browsers. What is less obvious is that many apps, like Slack, Notion, Microsoft Teams, Spotify, and Figma, are all web applications wrapped in a Mac or Windows shell with an added desktop icon to appear native to the platform. Over its three-decades-long legacy, the web has even adapted to platform shifts, with data indicating that nearly 30% of top iPhone apps are built using web technologies and developers using the same technologies to build applications for Apple’s new Vision Pro headset just days  after its unveiling last year.

No. of registered domains, adjusted to exclude free domains .tk, .cf, .ga, .gq, .ml. 2023E linearly extrapolated based on the trajectory from Q4’22 until Q3’23
Source: DNIB

Regardless of how the application software landscape evolves, one constant remains: the web continues to grow stronger — the Domain Name Industry report from November 2023 counts 350 million registered website domains. Moreover, the usage of web applications is surging, increasing at a rate of almost twice that of conventional applications. But the most telling indicator of the web’s strength is that nearly 90% all B2B software is now accessed through the web, according to product analytics solution Amplitude, essentially dominating the category.

Almost 90% of B2B software is accessed through the web

However, there’s more to the web’s story than its growth and resilience. Behind the scenes, a transformative shift is underway, with the technologies that have been the backbone of the web for decades now being disrupted by a new generation of categories. The change is exemplified by the decline of Traditional Content Management Systems (CMS) and website builders. WordPress, once powering over a quarter of the top websites on the internet, is experiencing a downtrend in adoption after nearly two decades of dominance. Similarly, its contemporaries, such as Drupal and Squarespace, are following the same trajectory.

Traditional CMS adoption across the top 100k websites
Source: BuiltWith

The waning appeal of platforms like WordPress is linked to their original design as comprehensive, all-in-one solutions. This design was highly efficient when the web’s capabilities were more limited. However, today’s web landscape has evolved to favour a more composable architecture, with developers now preferring to build software using an ecosystem of independent systems and components that communicate through APIs. This means they are not bound by the legacy foundation and restrictions of platforms like WordPress, and instead, it allows them to select the best tools for their specific needs.

In practice, this means that all the capabilities WordPress and the likes tried to provide as a monolithic all-in-one package are now being dismantled into specialised tools, each purpose-built for the one use case they replace. For example, we’re witnessing the emergence of Visual Website Builders like Webflow, which concentrate solely on creating websites, unlike WordPress’s combined content management approach. Simultaneously, we see the rise of “headless CMS” like Contentful, focusing exclusively on content management. Furthermore, to serve as the foundation for integrating these components, we see Frontend Cloud Platforms like Vercel gaining significant traction. To reduce the complexity for developers, these platforms provide “Web Development Frameworks”, which are specialised development kits for web applications specifically, with Vercel’s Next.js being one of the most prominent ones.

Source: BuiltWith

Looking at the adoption of new web technologies, it’s clear that their popularity is rapidly increasing, particularly among more prominent websites. For instance, the top 10 thousand websites use the Web Development Framework Next.js at a rate four times higher than the top 1 million websites. Similarly, the difference is even more pronounced at fivefold for the headless CMS Contentful.

This disparity in adoption rates can be attributed to the greater resources available to larger companies managing high-traffic websites. They often have more financial resources and access to skilled personnel, enabling them to embrace and implement emerging technologies more readily. This trend is further evidenced by the fact that these leading websites are often the first to phase out older technologies like WordPress.

Adoption of the prevalent traditional CMS WordPress
Source: BuiltWith

However, drawing a parallel with the historical adoption of technologies like WordPress during the height of the “old” web, we observe a pattern where such technologies eventually gained widespread popularity across all websites. If this trend continues, with traditional platforms gradually losing ground, the emerging web technologies and the companies behind them stand to capture a significant opportunity as their markets shift from early adopters to the predominant choice.

Adoption of emerging web technologies
Source: GP Bullhound Insights

Enquiries
For enquiries, please contact:
Gustav Fridell, Associate, at gustav.fridell@gpbullhound.com

Sources:

  1. xkcd, comic “Installing”
  2. What Web Can Do Today, website
  3. Evan Bacon, blog post “Who’s using Expo OSS in 2024”
  4. X (Twitter), tweet by @donadeldev on June 22, 2023
  5. DNIB, report “The Domain Name Industry Brief Quarterly Report”
  6. Amplitude, blog post “What’s Growing Faster: Apps or Websites?”
  7. Amplitude, report “2022 App vs. Website Trend Report”
  8. BuiltWith, website
  9. Gartner, report “Top Strategic Technology Trends for 2022”

*No information set out or referred to in this communication shall form the basis of any contract. The issue of this GP Bullhound blog posting (the “report”) shall not be deemed to be any form of binding offer or commitment on the part of GP Bullhound or any of its affiliates or subsidiaries. This report is provided for use by the intended recipient for information purposes only.
It is prepared on the basis that the recipients are sophisticated investors (so-called “professional clients” in the meaning of Annex II of Directive 2014/65/EU on markets in financial instruments, or their equivalent elsewhere) with a high degree of financial sophistication and knowledge. This report and any of its information is not intended for use by private or retail investors in the UK or any other jurisdiction where access, use or availability of this information would be unlawful.
This report does not provide personalized advice or recommendations of any kind. You, as the recipient of this report, acknowledge and agree that no person has nor is held out as having any authority to give any statement, warranty, representation, or undertaking on behalf of GP Bullhound in connection with the contents of this communication. Although the information contained in this report has been prepared in good faith, no representation or warranty, express or implied, is or will be made and no responsibility or liability is or will be accepted by GP Bullhound.
In particular, but without prejudice to the generality of the foregoing, no representation or warranty is given as to the accuracy, completeness or reasonableness of any projections, targets, estimates or forecasts contained in this report or in such other written or oral information that may be provided by GP Bullhound. The information in this report may be subject to change at any time without notice. GP Bullhound is under no obligation to provide you with any such updated information. All liability is expressly excluded to the fullest extent permitted by law. Without prejudice to the generality of the foregoing, no party shall have any claim for innocent or negligent misrepresentation based upon any statement in this report or any representation made in relation thereto. Liability (if it would otherwise but for this paragraph have arisen) for death or personal injury caused by the negligence (as defined in Section 65 of the Consumer Rights Act 2015) of GP Bullhound, or any of its respective affiliates, agents or employees, is not hereby excluded nor is damage caused by their fraud or fraudulent misrepresentation. This report should not be construed in any circumstances as an offer to sell or solicitation of any offer to buy any security or other financial instrument, nor shall they, or the fact of the distribution, form the basis of, or be relied upon in connection with, any contract relating to such action. The information contained in this report has no regard for the specific investment objectives, financial situation or needs of any specific entity and is not a personal recommendation to anyone. Persons reading this report should make their own investment decisions based upon their own financial objectives and financial resources and, if in any doubt, should seek advice from an investment advisor.
Forward-looking information is provided for illustrative purposes only and is not intended to serve as, and must not be relied upon as a guarantee, an assurance, a prediction or a definitive statement of fact or probability. Actual events and circumstances are difficult or impossible to predict and may differ from assumptions. Any and all opinions expressed are current opinions as of the date appearing on the documents included in this report. The information contained in this report should not be relied upon as being an independent or impartial view of the subject matter, and for the purposes of the rules and guidance of the Financial Conduct Authority (“the FCA”) and of Financial Industry Regulatory Authority (“FINRA”), this report shall not be viewed as research report and is considered marketing communication.
Thus, in accordance with COBS 12.2.18 of the FCA Handbook, its contents have not been prepared in accordance with legal requirements designed to promote the independence of investment research and it is not subject to any prohibition on dealing ahead of the dissemination of the report.
The individuals who prepared the information contained in this report may be involved in providing other financial services to the company or companies referenced in this report or to other companies who might be said to be competitors of the company or companies referenced in this report.
For US Persons: This report is distributed to US persons by GP Bullhound Inc. a broker-dealer registered with the SEC and a member of the FINRA. GP Bullhound Inc. is an affiliate of GP Bullhound Corporate Finance Ltd. All investments bear certain material risks that should be considered in consultation with an investors financial, legal and tax advisors. GP Bullhound Inc. engages in private placement and mergers and acquisitions advisory activities with clients and counterparties in the Technology and CleanTech sectors.
In addition, the persons involved in the production of this report certify that no part of their compensation was, or will be, directly or indirectly related to the specific views expressed in this report. As such, no person at GP Bullhound (including its members, directors, officers and/or employees) has received, or is authorized to accept, any inducement, whether monetary or in whatsoever form, in counterparty of promise to issue favorable coverage for the companies to which this report may relate.

Jonathan Cantwell, Partner & Head of Software at GP Bullhound, said: “Various trends shaped the Software landscape in Q4 2023. Application Performance Management solutions are seeing strong tailwinds due to the need for more observability, with the current market for APM tools looking to reach $19bn in 2030 from $9bn today. Open source software continues to drive innovation, with corporations and VCs developing frameworks to invest in open source platforms. Robotics Process Automation is also experiencing significant growth as businesses seek higher automation, and the RPA market is set to grow from ~$4bn today to $82bn by 2032.”

Matt Stamp, Partner in the Software team at GP Bullhound, commented: “On the dealmaking side, Q4 volumes picked up, driven by buy-outs of Alteryx, IRIS, EngageSmart and additional capital raising by Visma. Tech stocks posted a strong 2023 coming out of a 2022 slump, and growth in tech stocks is expected to continue in 2024 with optimism driven by a lower interest rate environment. Given pent-up demand, available capital, and assuming a more stable market environment, we expect consistent growth in M&A and buy-out volumes in 2024.”

Application Performance Management solutions gaining significance

  • APM and Artificial Intelligence are increasingly converging to enhance software applications’ monitoring, analysis, and optimisation. This enables automated solutions to be engaged, preventing downtime and performance degradation.
  • The APM market is growing significantly with the support of several tailwinds, primarily observability coupled with digital transformation and the increased reliance on software applications.

Security testing software is safeguarding digital landscapes

  • According to a IBM, the global average cost of a data breach in 2023 was $4.45m, a 15% increase over three years.
  • Polaris Market Research valued the global security testing market at $9.3bn in 2022, which is likely to reach $41.6bn by 2032, growing at a CAGR of 16.2%.

Open source software is increasing commercialisation

  • For-profit corporations are increasingly embracing open source to tap into community expertise to accelerate technology development despite limited commercial opportunities initially.
  • Over 30% of Fortune 100 companies have implemented Open Source Program Offices, while VCs are evaluating investments based on open source metrics like GitHub Stars, contributors, or Slack/Discord community sizes.

Robotic Process Automation is on the rise

  • As hyper-automation continues to be implemented in business operations, Robotic Process Automation has become increasingly used due to its ability to drive operational efficiencies, capture data, and perform routine tasks.
  • The market size for robotic process automation reached $3.7bn in 2022, and it is likely to grow to $81.8bn by 2032, at a CAGR of 36.6%.

Enquiries
For enquiries, please contact Jonathan Cantwell, Partner, at jonathan.cantwell@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.

Per Roman, Managing Partner, and Alec Dafferner, Partner at GP Bullhound, commented: “As we transition into 2024, the profound impact of artificial intelligence on technology and its future is undeniable. In a climate of economic uncertainty, AI is the cornerstone of our forecasts for the coming year. Key trends include the organisation of legacy data, the commoditisation of large language models, and the ongoing semiconductor shortage, driven by increasing demand for AI-optimised hardware. These developments are opening up new avenues, such as the revitalisation of space exploration. As we navigate this complex yet exhilarating landscape, our predictions for 2024 offer insights into the upcoming opportunities and challenges that await us all.”

Leveraging our deep experience in working with cutting-edge software and world-class entrepreneurs and benefiting from unique market insights across our global network, GP Bullhound proudly presents its Technology Predictions 2024.

Prediction 1: Large Language Models become smaller, disrupting the AI market

  • With the highest-performing AI models being closed-source and commercial, a counter-movement is emerging in the open-source community to develop smaller models which are just as performant, yielding better results in some cases

Prediction 2: Bits to billions: legacy data spurs acquisition boom

  • 90% of enterprise data is unstructured, but it’s no longer useless as companies turn to generative AI to improve operational efficiencies and unlock value within their data

Prediction 3: Private sector to spearhead space revitalisation

  • Satellites orbiting Earth to increase from c.8,000 today to over 100,000 in the next 10 years, with private sector companies leading a new space race as the industry goes commercial

Prediction 4: The rise of authenticity as creators challenge AI

  • Tools that obstruct AI from training off human-created content will surge next year as 2024 is geared to become a battleground between AI-generated and human-created content

Prediction 5: AR/VR & AI fuel a surge in immersive education investments

  • Enterprises are leveraging AR and VR to train and upskill  employees in unprecedented ways, especially in medical and high-risk professions, while demand for AI-powered learning is driving billions in funding for edtech companies

Prediction 6: Apple’s expanded subscription service with ad-free search engine

  • An Apple search engine to rival Google’s is the missing piece in the company’s internet strategy, despite the latter’s hefty annual payments of c.$20bn to be the default engine on iOS

Prediction 7: Anti-money laundering and payment protections come centre-stage

  • The number of regulatory compliance platforms is increasing as illicit wallets send c.20% of funds through DeFi, with the AML market, driven by digital transactions, poised to grow at a CAGR of 16% between 2023 and 2030

Prediction 8: AI is reshaping media with personalised content and acquisitions

  • AI was one of the few resilient areas in the 2023 market downturn, with $23bn in funding in the US alone; M&A activity and big takeovers are set for 2024 as businesses rethink entire offerings to harness its power to remain competitive

Prediction 9: AI race escalates semiconductor shortage

  • AI-driven applications are multiplying, adding strain on semis supply that caters to them, with large cloud providers in a race to invest in GPUs or risk falling behind

Prediction 10: Acceleration of carbon accounting as new regulations loom

  • A profound time for companies that offer automated carbon accounting software as businesses brace themselves for new government requirements for emissions calculations in 2024; only 10% comprehensively measured emissions last year as processes are overwhelmingly manual

Enquiries
For enquiries, please contact: insights@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.

Jonathan Cantwell, Partner & Head of Software at GP Bullhound, said: “In Q3, we have seen several trends drive the SaaS sector. Identity and Access Management solutions are becoming more prominent, as businesses face ongoing cybersecurity attacks; the sports management software sector is growing, with businesses seeking to streamline operations and engage fans; the BPM market is harnessing AI to refine processes, leading to better resource allocation. All being driven by multi-tenant SaaS solutions at the enterprise.”

Matt Stamp, Partner in the Software team at GP Bullhound, commented: “While global SaaS deal volumes continue to be subdued in Q3, market sentiment is improving in both public and private markets with SaaS IPOs back on the agenda. Both Klaviyo’s IPO and Splunk’s acquisition by Cisco are two examples of that sentiment which we expect to push into Q4 and 2024.”

Identity and Access Management solutions rising

  • The global IAM market size is likely to grow from $15.7bn in 2023 to $32.6bn by 2028, representing a CAGR of 15.6%
  • Accenture partnered with Identity Security company, CyberArk, to manage approved access across on-premises, cloud, and hybrid infrastructures. Oracle took similar steps to improve client governance and accessibility to data

Growing importance of threat intelligence platforms

  • The global threat intelligence market stood at $4.2bn in 2022, looking to expand from $4.9bn in 2023 to $18bn by 2030
  • Cyber threats are constantly evolving and threat intelligence programs adapt to these changes by gathering, analysing, and updating information about emerging risks

The advance of sports tech

  • The sports management software sector is experiencing robust growth, driven by increased demand from sports organisations seeking advanced solutions for streamlined operations and enhanced fan engagement
  • By harnessing advanced analytics and artificial intelligence, these solutions are revolutionising the operations of sports organisations, providing a comprehensive range of products and capabilities

Enquiries
For enquiries, please contact Jonathan Cantwell, Partner, at jonathan.cantwell@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.


This content is password-protected. To view it, please enter the password below.

Eric Crowley, Partner at GP Bullhound, commented: “The GP Bullhound team continues to be amazed at the companies and entrepreneurs building within the CSS ecosystem. The learnings and evolutions that have taken place over the last three years have been extremely exciting to watch. Companies have become experts at providing continuous value to consumers, and, in return, the consumers have expanded the type of services that they will subscribe to. GP Bullhound remains excited to help these companies reach for success.”

Market update

  • App stores are the largest markets in human history, with the Apple App Store larger than c.450 of the Fortune 500 by revenue, and Apple and Google stores together driving sales for five billion consumers globally
  • The fallout from Epic Games vs Apple spells advantages for developers, as Apple and Google reduce subscription fees, driving up the value of CSS applications
  • The proliferation of non-traditional media channels and the growing number of OTT options has disrupted the sports viewing landscape forever, driving subscriptions for streaming platforms with premium sports content
  • GP Bullhound’s CSS Index highlights past market turbulence but points towards stabilisation. M&A and private financing remain stable, with conversations increasing

CSS insights

  • Consumer companies innovate on how to build or buy missing pieces of the “3C Ice Cream Cone” – Content, Commerce & Community
  • The best founders do not overlook segmentation; unlocking value post-customer acquisition is key
  • Leading applications make the churn of a consumer friction-free with the goal of re-acquiring them when their need returns
  • Companies in fitness, mental health, education and prosumer explore adding B2B offerings to drive further revenue growth and reduce user churn
  • Time is ripe for a CSS “category killer” in family planning, AI, youth sports, wealth management, and news
  • A digital newsletter renaissance is underway as consumers are increasingly willing to pay for high-quality content
  • Meteoric interest in AI means many CSS players have embraced the technology, but deployments will have to prove true value-add to keep consumers subscribing
  • Traditional B2B tools are still the backbone of many CSS companies in managing key functions

Insights from company builders

  • Joel Gratz, CEO, OpenSnow
  • Matthew Fox, CEO, SpotGamma
  • Vince Mayfield, CEO, TalkingParents
  • Ben Spero, Managing Director, Spectrum Equity
  • Helen Christakos, Partner, Allen & Overy
  • Jessie Cai, Vice President, General Atlantic

Enquiries
For enquiries, please contact:
Eric Crowley, Partner, at eric.crowley@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.

Claudio Alvarez, Partner at GP Bullhound, commented: “Several trends emerged across the fintech space in Q2: the sector is catalysing the evolution of ESG, with multiple applications at the intersection of both, including data and analytics, impact reporting, and sustainable investment solutions; the digital payment revolution continues, with more customers than ever owning three or more digital wallets, and, lastly, we are seeing increasing potential for institutions to revisit crypto launches on the back of a solid crypto start this year.”

Fintech is catalysing the evolution of an ESG-centric world

  • The increasing importance of ESG has had a material impact on the Fintech sector
  • Combining core ESG principles with financial technology has revolutionised the way businesses and investors approach sustainable and responsible practices
  • The integration of ESG into Fintech has multiple applications, including ESG data and analytics, sustainable investment solutions, impact measurement and reporting, and ESG risk management

Embracing the continued digital payment revolution

  • The global digital payments market is set to grow at 18% compound annual growth from 2022-2030
  • The surge of Fintech has paved the way for the rise of digital wallets, a trend that is reshaping consumer habits. Recent statistics indicate that customers own three or more digital wallets, from 18% in 2021 to 30% in 2022
  • In the US alone households collectively pay c.15 billion bills each year. To streamline this process, mobile banking solutions equipped with push notifications and real-time payment confirmation are in high demand

Institutionals could be positioning for a crypto comeback

  • The cryptocurrency market is currently experiencing a strong momentum following a solid start in 2023 thanks to changing global macroeconomic conditions and declining inflation data
  • On the back of this positive sentiment, some institutions are revisiting the opportunity to get exposure to this asset class via Exchange Traded Funds
  • Many cryptocurrency executives think that BlackRock’s proposed ETF could be the first spot bitcoin vehicle to be accepted by the Securities and Exchange Commission (SEC) in the US

Enquiries
For enquiries, please contact Claudio Alvarez, Partner, at claudio.alvarez@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.

Oliver Schweitzer and Ravi Ghedia, Executive Directors at GP Bullhound, said: “We have seen various trends shaping the Digital Services landscape in Q2. Low-code solutions are reducing pressure on developers, turning non-technical users into ‘citizen developers’; continuous development in visual effects is revolutionising how brands think about digital marketing; a growing push towards composable platforms is seeing increased fundraising and M&A activity across composable tech providers and firms specialised in composable strategy and implementation. On the dealmaking side, Q2 deal volumes reduced to in line with Q2 2020, but agency group activity remained high with WPP, Publicis and Dentsu being very active.”

Low-code continuing to democratise development

  • Low-code solutions have reduced development friction, making non-technical users “citizen developers”
  • The global low-code development technologies market is set to be worth ~$32bn by 2024, growing strongly at a CAGR of 20%
  • By 2026 developers outside formal IT departments could account for at least 80% of the user base for low-code development tools

Continuous development in virtual effects is pioneering innovation in digital

  • Visual effects (VFX), once considered an exclusive art only available for big-budget Hollywood productions, is increasingly becoming a necessity within digital marketing
  • VFX has continued to grow in popularity with the current market size at $9.95bn in 2022, and likely to grow at a CAGR of 10.4% to reach over $18.02bn by 2028.
  • It is likely that the advertising segment of this spend will grow even faster at a CAGR closer to 15% per annum

Composable reshaping Digital Experiences

  • Customer experience expectations are rapidly changing in a digital-first environment with traditional monolithic platforms rapidly supplemented with highly-flexible best-of-breed composable platforms
  • 2023 has seen M&A activity in the sector, including the acquisition of Unstack by Elastic Path, the acquisition of Gatsby by Netlify, and on the services side, the acquisition of Corra by Publicis Sapient
  • The composable application market size is estimated at $5.2bn in 2023 and likely to reach $11.8bn by 2028, at a CAGR of 17.5%

Enquiries
For enquiries, please contact:
Oliver Schweitzer, Executive Director (US), at oliver.schweitzer@gpbullhound.com
Ravi Ghedia, Director (Europe), at ravi.ghedia@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.

Alec Dafferner, Partner at GP Bullhound, said: “In this quarterly report, we have highlighted several key trends driving the sector: the rise of video games movies and series is forcing Hollywood and investors to look at significant investments in this market; AI-driven content creation is growing, and future iterations will focus on hyper-personalisation, prototype acceleration and predictive analysis; major AR/VR headset releases this year show that the gaming world is continuing to evolve toward more realistic experiences and the pipeline of new titles for this market is promising. While market conditions remain uncertain, the GP Bullhound Digital Media diversified indices had a great quarter, rising by c. 8.8% compared to Q1 2023.”

The renaissance of video game movies and series

  • The video game industry has experienced remarkable growth, generating an annual revenue of close to $100bn in the US alone
  • Now, adaptations of video games are becoming highly-successful, with The Super Mario Brothers movie and the HBO Series The Last of Us being met with strong critical acclaim and box office success
  • Given the success and potential to foster closer ties between two previously distinct sectors of the entertainment industry, Hollywood and investors are set to make significant investments in this market

Content providers increasingly relying on AI to streamline creation process

  • The creative industry has seen an increase in the use of AI, allowing content providers to automate tasks, reduce their costs, increase their precision, and curate better user experiences
  • All AI tools used have as a main goal the optimisation of practices, where AI and NLP algorithms allow for scalable content creation and efficient content methods
  • Future trends in the industry include hyper-personalisation, prototype acceleration and predictive analysis

Growing pipeline of high-quality AR and VR games

  • AR and VR scored gains during the pandemic as the pursuit of high-quality entertainment fueled interest in VR accessories such as headsets, controllers, and bodysuits
  • In 2023, AR and VR continue to gain traction in the gaming industry as players increasingly seek realistic experiences. AR and VR games are creating new levels of engagement and immersion
  • Competition between providers of AR/VR accessories is intensifying as tech giants including Meta, Sony, HTC, and Apple announced new headsets this year

Enquiries
For enquiries, please contact Alec Dafferner, Partner, at alec.dafferner@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s best entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.

Alessandro Casartelli, Executive Director at GP Bullhound, said: “In our latest report, we have highlighted the key digital commerce trends in Q2 2023. Virtual dressing room technology becomes mainstream thanks to AI, drone deliveries are growing in popularity as a quicker and more cost-effective delivery method, and public-to-private deals and hostile takeovers attempts have made a comeback as some companies are perceived as undervalued. While the IPOs remain quiet and valuations are still off their highs, the market is showing initial signs of recovery.”

“Virtual dressing room” technology enters the mainstream thanks to AI

  • Google’s new tool lets customers try on clothes virtually, revolutionising the way consumers shop for clothes online. Until now, augmented reality has had limited success in bringing virtual dressing into the mainstream
  • The capability is similar to a store assistant bringing customers choices based on colour, style, patterns and price. Unlike a physical shop, it’s not limited to in-stock inventory and can recommend products to shoppers across brands
  • AI and virtual dressing rooms could significantly reduce the number of returns, creating savings for ecommerce retailers. Fewer returns will also limit the fashion industry’s negative impact on the climate

Drones proving to be a more convenient and sustainable delivery option

  • Studies show drones could result in cost savings of 70% for ecommerce companies when compared to more conventional techniques
  • The ecologically benign aspect of drone delivery can draw in clients who are concerned about the environment. PwC predicts a reduction of 2.4 million tons of carbon by 2030, which is equivalent to removing 1.7 million cars from the road for a year
  • Governments and aviation authorities are working to establish guidelines and regulations to ensure safe and responsible drone operations

Take privates and hostile takeover attempts for seemingly undervalued assets

  • P2P transactions on the rise as private equity investors are willing to take a longer-term view than their public equivalents
  • Valuation also plays a part – volatility in public markets has long equated in opportunities for both public and private investors to discover undervalued stocks
  • While takeover opportunities exist, the right valuation will always be important and investors need to find the right balance between value and capitalisation

Enquiries
For enquiries, please contact:
Alessandro Casartelli, Executive Director, at alessandro.casartelli@gpbullhound.com

About GP Bullhound
GP Bullhound is a leading technology advisory and investment firm, providing transaction advice and capital to the world’s entrepreneurs and founders. Founded in 1999 in London and Menlo Park, the firm today has 14 offices spanning Europe, the US and Asia.